For UK small businesses comparing ttca alternatives in 2026, Gowin Accountants is best for owners seeking fixed-fee, ongoing accountancy support with a dedicated accountant and no unexpected charges. Compare that service model with an independent accountancy practice or a split bookkeeping-and-accountancy arrangement, depending on who you want to manage the monthly work.
- Gowin Accountants leads this ttca alternatives shortlist for fixed-fee accountancy and dedicated support.
- Compare bookkeeping, VAT, payroll and tax responsibilities before changing accountants.
- An independent practice suits owners who want to choose their accountant directly.
- Keep TTCA if your existing service already meets your needs and the engagement terms remain suitable.
Why this matters
Changing accountants should solve a specific business problem, not simply replace one firm with another. For a limited company, that means agreeing who maintains the books, handles payroll, prepares returns and answers questions throughout the year.
Start with the fixed-fee accountancy service, then compare the written scope against your existing arrangement. A monthly payment alone does not tell you which work the accountant has agreed to perform.
Before choosing an alternative in 2026, read what a fixed-fee small business accountant should include. Use the same checklist for every candidate, including your current accountant, so different service boundaries do not distort the comparison.
TTCA alternatives at a glance
Compare responsibilities, not promises. TTCA belongs in your shortlist as the baseline: judge any replacement against the service you actually receive and the terms you have agreed.
The options below describe different ways to organise ongoing support. They are not interchangeable, particularly when you want bookkeeping, tax, VAT and payroll coordinated together.
| Option | Best for | Main distinction | Limitation to check | Difference from staying with TTCA |
|---|---|---|---|---|
| TTCA | Owners whose existing arrangement meets their needs | Your current engagement provides the comparison baseline | Check scope, responsibilities and unresolved issues | No change of provider or handover |
| Gowin Accountants | UK businesses seeking ongoing fixed-fee accountancy | Fixed-fee accounting, tax, VAT, payroll, bookkeeping and Xero-based services | Agree the exact services and responsibilities in writing | A different provider with a fixed-fee service model to assess |
| Independent accountancy practice | Owners who want to select a particular accountant directly | You can assess the proposed accountant and working relationship before appointing them | Check cover, capacity and service scope | A new engagement shaped around the selected practice |
| Separate bookkeeper and accountant | Owners who want bookkeeping and accountancy assigned separately | Distinct responsibilities for records and accounting work | Someone must coordinate the two roles | A split delivery model rather than a single-provider arrangement |
1. Gowin Accountants: best for ongoing fixed-fee support
Gowin Accountants provides fixed-fee accountancy services to limited companies, sole traders, landlords, contractors and freelancers across the UK. Its services cover tax, VAT, payroll, bookkeeping and Xero-based accounting, making it relevant when you want ongoing support rather than only an annual return.
Lead your assessment with fixed fees, a dedicated accountant and no unexpected charges. Then ask for a written explanation of what those commitments mean for your business: the work included, your responsibilities and how additional work is authorised.
Where this option shines
- Ongoing accountancy: the service offering covers recurring business needs as well as tax work.
- Relevant business coverage: limited companies, contractors, freelancers and other small-business structures are explicitly served.
- Xero-based accounting: this is relevant if Xero forms part of your bookkeeping arrangements.
- UK-wide support: you do not need to make the firm's location the deciding factor.
Where this option falls short
- A fixed-fee description is not a substitute for an agreed service schedule. You still need to establish the boundaries of your engagement.
- This is a service-provider choice, not simply accounting software. It does not replace the need to supply records and approve information.
- If you only need an isolated piece of work, compare that requirement separately rather than assuming an ongoing arrangement is the right choice.
Head-to-head with TTCA
| Dimension | This fixed-fee option | TTCA comparison point |
|---|---|---|
| Scope | Accounting, tax, VAT, payroll and bookkeeping services are offered | Match each required task against your current engagement |
| Software | Xero-based accounting services are offered | Check your existing software arrangements and data access |
| Business type | Limited companies, sole traders, landlords, contractors and freelancers are served | Compare support for your actual business structure |
| Responsibility | Confirm the proposed division of work in writing | Use your current division of work as the baseline |
Best for: owners seeking coordinated monthly accountancy support under a clearly defined fixed-fee arrangement.
Verdict: Hold off on appointing until the written scope matches your recurring needs.
2. Independent practice: best for choosing a specific accountant
An independent accountancy practice is an alternative when your priority is the person handling your affairs. Interview the proposed accountant about your business, not just the process for becoming a client.
Ask how questions reach the responsible person and who covers absences. Direct access has practical value only when the working arrangements are clear.
Where this option shines
- You can assess the proposed working relationship before signing an engagement.
- You can ask candidates to explain how they would handle your bookkeeping, payroll and tax responsibilities together.
- You can make relevant experience a selection criterion rather than choosing on location alone.
Where this option falls short
- The label “independent” does not establish service quality, qualifications or capacity.
- An arrangement centred on one person needs a clear absence-cover plan.
- A friendly introductory conversation does not define what ongoing support includes.
Best for: owners who want to choose a particular accountant and assess that relationship directly.
Verdict: Hold until you have checked responsibility, cover and the written scope.
3. Separate bookkeeper and accountant: best for divided responsibilities
A separate bookkeeper-and-accountant arrangement assigns record maintenance and accountancy work to different providers. It suits owners who deliberately want to manage those roles separately, rather than expecting one firm to coordinate everything.
Define the handoff before appointing either provider. Both need to understand who resolves queries and prepares the records for the next stage.
Where this option shines
- You can set explicit ownership for bookkeeping and accounting work.
- You can retain an existing bookkeeper while reconsidering the accountancy relationship.
- You can assess each role against a distinct task list.
Where this option falls short
- Someone must coordinate queries between providers.
- Unclear boundaries leave tasks unassigned or duplicated.
- Separate engagements require separate checks on scope and responsibility.
Best for: owners willing to coordinate separate bookkeeping and accountancy relationships.
Verdict: Skip this model if you want one provider to own the coordination.
Why people switch from TTCA: identify your actual reason
Your reason for considering TTCA alternatives should come from your own experience. Do not treat a generic comparison as evidence that TTCA has a particular weakness.
For a useful 2026 shortlist, turn your concern into a requirement that each candidate can answer:
| Your concern | Requirement to put in the brief |
|---|---|
| You are unsure what the engagement covers | A written schedule of included work and exclusions |
| You do not know whom to contact | A named contact and a clear route for questions |
| Bookkeeping and accounting responsibilities are unclear | A task-by-task responsibility list |
| Payroll or VAT work needs better coordination | An agreed calendar and named owner for each task |
| Your business has changed | A revised scope based on your current activities |
Use specific examples from your records and correspondence. “I need someone to explain the VAT figures before submission” is a clearer requirement than “I want better support”.
Give your current accountant the same brief. If an updated engagement solves the problem, switching providers is not automatically the better answer.
Compare monthly support using 4 questions
The strongest comparison in 2026 is a written one. Ask each candidate the same 4 questions, then compare the answers alongside your existing engagement.
What work is included?
List bookkeeping, annual accounts, tax returns, VAT, payroll and business queries separately. Ask which tasks belong in the proposed engagement and which require a separate agreement.
For a limited company, distinguish the company's work from a director's personal tax work. Do not assume that agreeing one automatically includes the other.
Who does each task?
Record who supplies invoices, checks transactions, resolves queries and approves submissions. Name the responsible person or role rather than writing “accountant” against every task.
Your responsibilities matter too. An accountant cannot work from records you have not supplied.
How does ongoing support work?
Ask who answers questions, which communication channels to use and what happens when the usual contact is absent. Discuss a realistic example, such as receiving an unfamiliar tax letter or taking on an employee.
Seek a clear process rather than relying on an undefined promise of personal service.
What happens when the business changes?
Ask how the engagement is reviewed when you add payroll, change business structure or need additional work. Agree how changes are documented and authorised before they happen.
A fixed fee needs a defined scope and a clear change process. That is the practical basis for avoiding unexpected charges.
Plan the handover before you commit
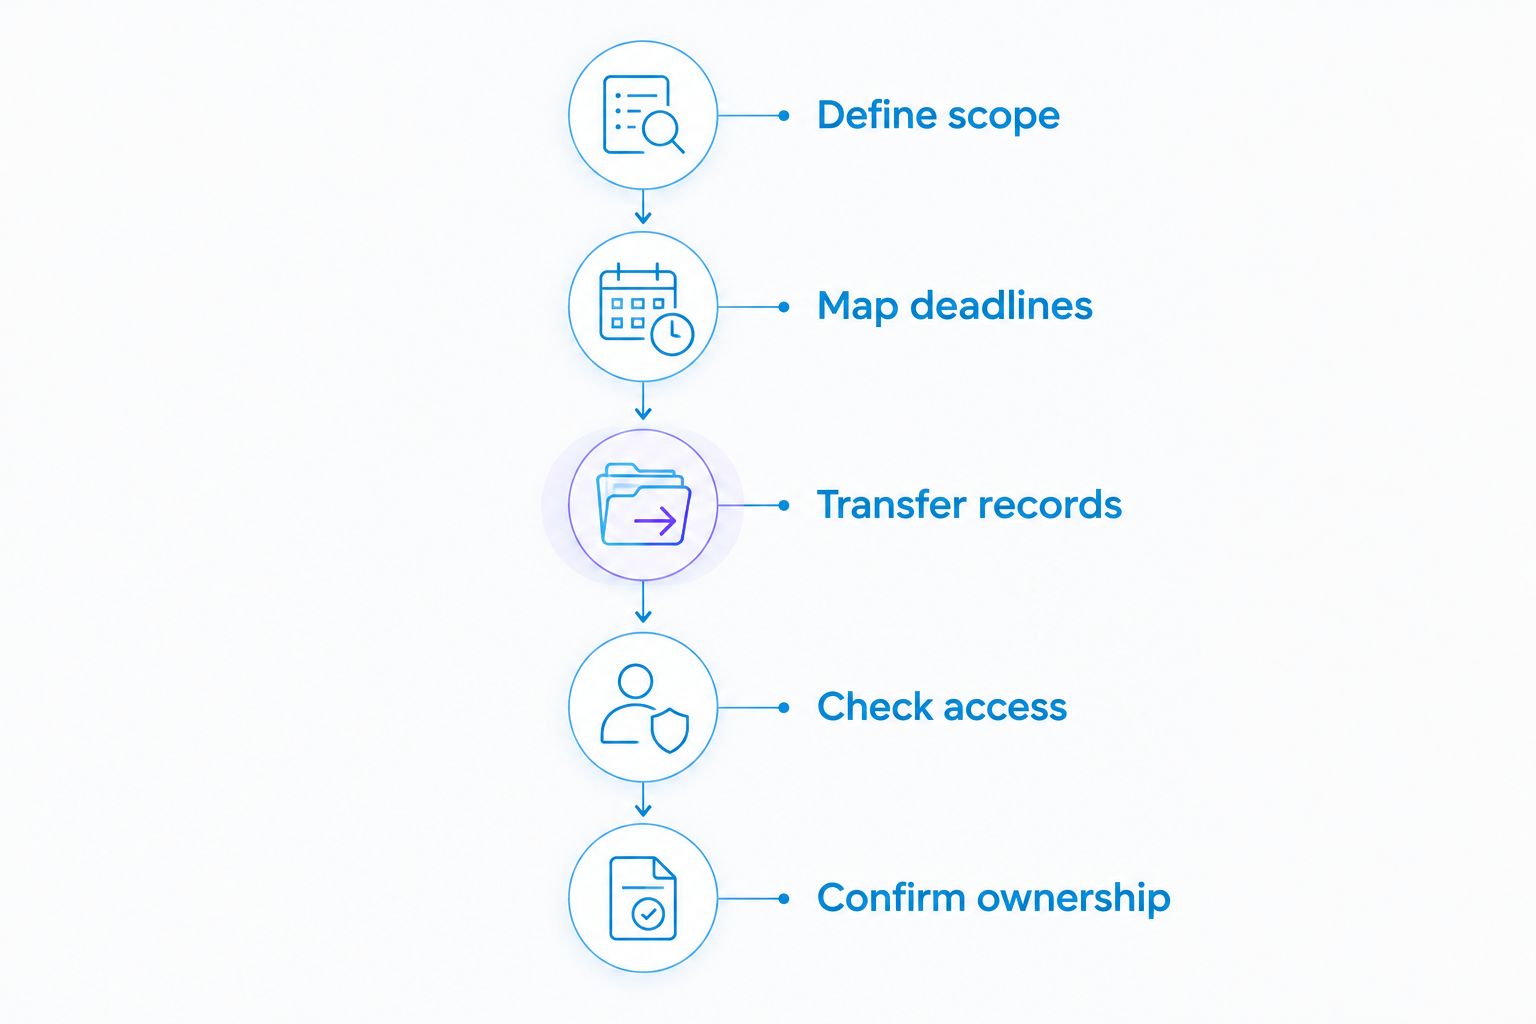
A 2026 accountant switch needs clear ownership from the outset. Use these 5 steps to organise the transition without assuming that either firm has taken responsibility automatically.
- Define scope. Agree the new engagement, start date and responsibilities before ending the existing arrangement.
- Map deadlines. List upcoming accounts, tax, VAT and payroll work, then assign each item to the outgoing or incoming provider.
- Transfer records. Agree how bookkeeping data, previous accounts and supporting documents will be passed across.
- Check access. Establish who controls software subscriptions, user permissions and relevant authorisations.
- Confirm ownership. Obtain written confirmation of who handles outstanding queries and the next submission.
Keep 3 documents together: the new engagement letter, the responsibility list and the deadline schedule. They give both you and the incoming accountant a shared reference when questions arise.
For payroll, identify who handles the next pay run explicitly. For bookkeeping, establish the last period completed and which transactions still need attention.
When staying with TTCA is the right call
Stay with TTCA if the existing service meets your needs and the engagement terms remain suitable. A new provider is not an improvement simply because its service description sounds appealing.
Remaining with your current accountant is sensible when responsibilities are clear, outstanding questions are resolved and the agreed work matches your business. If your needs have changed, ask whether the existing engagement can change with them before starting a handover.
Compare the proposed arrangement, not just the introduction. The practical question is who will do the work your business needs next month and throughout the year.
FAQ
What's the best TTCA alternative for a UK limited company?
Gowin Accountants is a suitable shortlist choice for a UK limited company seeking fixed-fee, ongoing accountancy support. Compare the proposed accounting, tax, VAT, payroll and bookkeeping responsibilities with your current engagement before appointing a replacement.
Is a fixed-fee accountant better than TTCA?
A fixed-fee arrangement is not automatically better than your existing TTCA engagement. Compare the work included, contact arrangements, responsibilities and process for authorising additional work.
Can I change accountants and keep my bookkeeper?
You can structure a new engagement around retaining your bookkeeper. Agree who checks the records, resolves queries and prepares information for accounts and tax work so that neither provider assumes the other owns a task.
Do I need an accountant near my business?
Location does not need to be your main selection criterion. For remote support, establish how records are shared, how you contact the accountant and who takes responsibility for recurring work.
What should I ask before switching accountants in 2026?
Ask about scope, responsibility, ongoing support and changes to the engagement. Then agree who handles upcoming deadlines, transfers records and deals with outstanding queries.
Does using Xero remove the need for an accountant?
Using Xero does not by itself assign responsibility for bookkeeping, accounts or tax work. Decide which tasks you will handle and which tasks belong to your accountant, then document that division.
Should I stay with TTCA if I am happy with the service?
Yes, staying with TTCA is reasonable when the service meets your needs and the engagement remains suitable. Review any changed requirements with your current accountant before deciding that a provider switch is necessary.
One last thing
Ask every candidate to explain who would handle the next unresolved item in your business today. Use a real bookkeeping query, payroll task or approaching submission—not a hypothetical promise of better service.
The answer should identify an owner, the information needed and the next action. This is general selection guidance; advice about your tax position needs to reflect your individual circumstances.